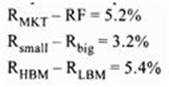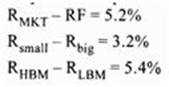CFA-Institute certification preparation

CFA-LEVEL-II Practice Questions

Practice exam-style questions, check your answers, and review explanations and source references where they are available.

Exam
CFA-LEVEL-II
Provider
CFA-Institute
Full set
715 questions
Last Update Check

Streamline your study routine for the CFA-LEVEL-II exam with the expertly crafted materials available at Cert Mage. Our digital platform boasts a comprehensive CFA-LEVEL-II question bank explicitly designed to quickly identify and close your knowledge gaps. Experience the rigorous format of the actual test by utilizing our intuitive exam simulator. We encourage all candidates to initially test their skills with our CFA-LEVEL-II sample questions. From there, our premium CFA-LEVEL-II exam questions and in-depth practice questions will provide all the necessary insights to pass on your first attempt.

Martha Gillis, CFA, trades currencies for Trent, LLC. Trent is one of the largest investment firms in the world, and its foreign currency department trades more currency on a daily basis than any other firm. Gillis specializes in currencies of emerging nations. Gillis received an invitation from the new Finance Minister of Binaria, one of the emerging nations included in Gillis's portfolio. The minister has proposed a number of fiscal reforms that he hopes will help support Binaria's weakening currency. He is asking currency specialists from several of the largest foreign exchange banks to visit Binaria for a conference on the planned reforms. Because of its remote location, Binaria will pay all travel expenses of the attendees, as well as lodging in government-owned facilities in the capital city. As a further inducement, attendees will also receive small bags of uncut emeralds (as emeralds are a principal export of Binaria), with an estimated market value of $500. Gillis has approximately 25 clients that she deals with regularly, most of whom are large financial institutions interested in trading currencies. One of the services Gillis provides to these clients is a weekly summary of important trends in the emerging market currencies she follows. Gillis talks to local government officials and reads research reports prepared by local analysts, which are paid for by Trent. These inputs, along with Gillis's interpretation, form the basis of most of Gillis's weekly reports. Gillis decided to attend the conference in Binaria. In anticipation of a favorable reception for the proposed reforms, Gillis purchased a long Binaria currency position in her personal account before leaving on the trip. After hearing the finance minister's proposals in person, however, she decides that the reforms are poorly timed and likely to cause the currency to depreciate. She issues a negative recommendation upon her return. Before issuing the recommendation, she liquidates the long position in her personal account but does not take a short position. Gillis's supervisor, Steve Howlett, CFA, has been reviewing Gillis's personal trading. Howlett has not seen any details of the Binaria currency trade but has found two other instances in the past year where he believes Gillis has violated Trent's written policies regarding trading in personal accounts. One of the currency trading strategies employed by Trent is based on interest rate parity. Trent monitors spot exchange rates, forward rates, and short-term government interest rates. On the rare occasions when the forward rates do not accurately reflect the interest differential between two countries, Trent places trades to take advantage of the riskless arbitrage opportunity. Because Trent is such a large player in the exchange markets, its transactions costs are very low, and Trent is often able to take advantage of mispricings that are too small for others to capitalize on. In describing these trading opportunities to clients, Trent suggests that "clients willing to participate in this type of arbitrage strategy are guaranteed riskless profits until the market pricing returns to equilibrium." Trent's arbitrage trading based on interest rate parity is successful mostly due to Trent's large size, which provides it with an advantage relative to smaller, competing currency trading firms. Has Trent violated CFA Institute Standards of Professional Conduct with respect to its trading strategy or its guarantee of results?
Answer options
MediSoft Inc. develops and distributes high-tech medical software used in hospitals and clinics across the United States and Canada. The firm's software provides an integrated solution to monitoring, analyzing, and managing output from a variety of diagnostic medical equipment including MRls, CT scans, and EKG machines. MediSoft has grown rapidly since its inception ten years ago, averaging 25% growth in sales over the last decade. The company went public three years ago. Twelve months after their IPO, MediSoft made two semiannual coupon bond offerings, the first of which was a convertible bond. At the time of issuance, the convertible bond had a coupon rate of 7.25%, par value of $1,000, a conversion price of $55.56, and ten years until maturity. Two years after issuance, the bond became callable at 102% of par value. Soon after the issuance of the convertible bond, the company issued another series of bonds which were putable, but contained no conversion or call features. The putable bonds were issued with a coupon of 8.0%, par value of $1,000, and 15 years until maturity. One year after their issuance, the put feature of the putable bonds became active, allowing the bonds to be put at a price of 95% of par value, and increasing linearly over five years to 100% of par value. MediSoft's convertible bonds are now trading in the market for a price of $947 with an estimated straight value of $917. The company's putable bonds are trading at a price of $1,052. Volatility in the price of MediSoft's common stock has been relatively high over the last few months. Currently the stock is priced at $50 on the New York Stock Exchange and is expected to continue its annual dividend in the amount of $1.80 per share. High-tech industry analysts for Brown & Associates, a money management firm specializing in fixed- income investments, have been closely following MediSoft ever since it went public three years ago. In general, portfolio managers at Brown & Associates do not participate in initial offerings of debt investments, preferring instead to see how the issue trades before considering taking a position in the issue. Since MediSoft's bonds have had ample time to trade in the marketplace, analysts and portfolio managers have taken an interest in the company's bonds. At a meeting to discuss the merits of MediSofVs bonds, the following comments were made by various portfolio managers and analysts at Brown & Associates: "Choosing to invest in MediSoft's convertible bond would benefit our portfolios in many ways, but the primary benefit is the limited downside risk associated with the bond. Since the straight value will provide a floor for the value of the convertible bond, downside risk is limited to the difference between the market price of the bond and the straight value." "Decreasing volatility in the price of MediSoft's common stock as well as increasing volatility in the level of interest rates are expected in the near future. The combined effects of these changes in volatility will be a decrease in the price of MediSoft's putable bonds and an increase in the price of the convertible bonds. Therefore, only the convertible bonds would be a suitable purchase." Assuming that portfolio managers at Brown & Associates purchased the convertible bonds, how many years would it take to recover the premium per share?
Answer options
Barton Wilson, a junior analyst, is a new hire at a money center bank. He has been assigned to help Juanita Chevas, CFA, in the currency trading department. Together, Wilson and Chevas are working on the development of new trading software designed to detect profitable opportunities in the foreign exchange market. Obviously, they are interested in risk-free arbitrage opportunities. However, they have also been instructed to investigate the possibility of longer-term currency exposures that are not necessarily risk-free. To test the logic of their new software, Wilson gathers the following market data: • Spot JPY/USD exchange rate = 120. • Spot EUR/USD exchange rate = 0.7224. • U.S. risk-free interest rate = 7%. • Eurozone risk-free rate = 9.08%. • Japanese risk-free rate = 3.88%. • Yield curves in all three currencies are flat. In addition to in-house currency transactions, the new software program is also intended to provide insight into currency exposure and hedging needs for the bank's major customers. These customers typically include large multinational firms. Essentially, the bank wants to provide consulting services to its clients concerning which currency exposures offer the greatest possibility of appreciation. In this process, the bank will rely on deviations from international parity conditions as an indicator of long-term currency movements. Wilson obtains the following data from the econometrics department: • JPY/USD spot rate one year ago =116. • EUR/USD spot rate one year ago = 0.7200. • Anticipated and historical U.S. annual inflation = 3%. • Anticipated and historical Japanese annual inflation = 0%. • Anticipated and historical Eurozone annual inflation = 5%. One of the bank's major customers has significant portions of its business in Japan, and the Eurozone and has long exposure to both currencies. The customer has traditionally hedged all currency risk. However, the customer's new risk manager has decided to leave some currency exposure unhedged in an attempt to profit from long-term currency exposure. Wilson wants to approximate the forward discount/premium for the JPY against the USD 12 months from now. According to the approximate version of interest rate parity, the JPY would most likely trade at a:
Answer options
Yi Tang updates several economic parameters monthly for use by the analysts and the portfolio managers at her firm. If economic conditions warrant, she will update the parameters even more frequently. As a result of an economic slowdown, she is going through this process now. The firm has been using an equity risk premium of 5.6%, found with historical estimates. Tang is going to use an estimate of the equity risk premium found with a macroeconomic model. By comparing the yields on nominal bonds and real bonds, she estimates the inflation rate to be 2.6%. She expects real domestic growth to be 3.0%. Tang does not expect a change in price/earnings ratios. The yield on the market index is 1.7% and the expected risk-free rate of return is 2.7%. Elizabeth Trotter, one of the firm's portfolio Managers, asks Tang about the effects of survivorship bias on estimates of the equity risk premium. Trotter asks, "Which method is most susceptible to this bias, historical estimates, Gordon growth model estimates, or survey estimates?" Tang wishes to estimate the required rate of return for Northeast Electric (NE) using the Capital Asset Pricing Model (CAPM) and the Fama-French three factor model. She is using the following information to accomplish this: · The risk-free rate of return is 2.7%. · The expected risk premiums arc: CFA Institute CFA LEVEL II question · The beta coefficient in the CAPM is estimated to be 0.63. · The betas (factor sensitivities) for the three Fama-French factors are 1.00 for the market factor, - 0.76 for the size factor, and -0.04 for the book-to-markct factor. Trotter also asks Tang about adjusted betas. She says, "We use a formula for the adjusted beta where the adjusted beta = (2/3) (regression beta) + (1/3) (1.0). How do the adjusted betas compare to the original regression betas?" Trotter has one final question for Tang. Trotter says, "We need to estimate the equity beta for VixPRO, which is a private company that is not publicly traded. We have identified a publicly traded company that has similar operating characteristics to VixPRO and we have estimated the beta for that company using regression analysis. We used the return on the public company as the dependent variable and the return on the market index as the independent variable. What steps do I need to take to find the beta for VixPRO equity? The companies have different debt/equity ratios. The debt of both companies is very low risk, and I believe I can ignore taxes." The estimate of the equity risk premium found with a macroeconomic model and the estimates determined by Tang is closest to:
Answer options
Glenda Garvey is interning at Samson Securities in the summer to earn money for her last semester of studies for her MBA, She took the Level 3 CFA® exam in June but has not yet received her score. Garvey's work involves preparing research reports on small companies. Garvey is at lunch with a group of co-workers. She listens to their conversation about various stocks and takes note of a comment from Tony Topel, a veteran analyst. Topel is talking about Vallo Engineering, a small stock he has tried repeatedly to convince the investment director to add to the monitored list. While the investment director does not like Vallo, Topel has faith in the company and has gradually accumulated 5,000 shares for his own account. Another analyst, Mary Kennedy, tells the group about Koral Koatings, a paint and sealant manufacturer. Kennedy has spent most of the last week at the office doing research on Koral. She has concluded that the stock is undervalued and consensus earnings estimates are conservative. However, she has not filed a report for Samson, nor does she intend to. She said she has purchased the stock for herself and advises her colleagues to do the same. After she gets back to the office, Garvey purchases 25 shares of Vallo and 50 shares of Koral for herself. Samson pays its interns very little, and Garvey works as a waitress at a diner in the financial district to supplement her income. The dinner crowd includes many analysts and brokers who work at nearby businesses. While waiting tables that night, Garvey hears two employees of a major brokerage house discussing Metrona, a nanotechnology company. The restaurant patrons say that the broker's star analyst has issued a report with a buy rating on Metrona that morning. The diners plans to buy the stock the next morning. After Garvey finishes her shift, restaurant manager Mandy Jones, a longtime Samson client, asks to speak with her. Jones commends Garvey for her hard work at the restaurant, praising her punctuality and positive attitude, and offers her two tickets to a Yankees game as a bonus. The next morning, Garvey buys 40 shares of Metrona for her own account at the market open. Soon afterward, she receives a call from Harold Koons, one of Samson's largest money-management clients. Koons says he got Garvey's name from Bertha Witt, who manages the Koons' account. Koons wanted to reward the analyst who discovered Anvil Hammers, a machine-tool company whose stock soared soon after it was added to his portfolio. Garvey prepared the original report on Anvil Hammers. Koons offers Garvey two free round-trip tickets to the city of her choice. Garvey thanks Koons, then asks her immediate supervisor, Karl May, about the gift from Koons but does not mention the gift from Jones. May approves the Koons' gift. After talking with May, Garvey starts a research project on Zenith Enterprises, a frozen-juice maker. Garvey's gathers quarterly data on the company's sales and profits over the past two years. Garvey uses a simple linear regression to estimate the relationship between GDP growth and Zenith's sales growth. Next she uses a consensus GDP estimate from a well-known economic data reporting service and her regression model to extrapolate growth rates for the next three years. Later that afternoon, Garvey attends a company meeting on the ethics of money management. She listens to a lecture in which John Bloomquist, a veteran portfolio manager, talks about his job responsibilities. Garvey takes notes that include the following three statements made by Bloomquist: Statement 1: I'm not a bond expert, and I've turned to a colleague for advice on how to manage the fixed-income portion of client portfolios. Statement 2: I strive not to favor either the remaindermen or the current-income beneficiaries, instead I work to serve both of their interests. Statement 3: All of my portfolios have target growth rates sufficient to keep ahead of inflation. Garvey is not working at the diner that night, so she goes home to work on her biography for an online placement service. In it she makes the following two statements: Statement 1: I'm a CFA Level 3 candidate, and I expect to receive my charter this fall. The CFA program is a grueling, 3-part, graduate-level course, and passage requires an expertise in a variety of financial instruments as well as knowledge of the forces that drive our economy and financial markets. Statement 1: I expect to graduate with my MBA from Braxton College at the end of the fall semester. As both an MBA and a CFA, I'll be in high demand. Hire me now while you still have the chance. During the lunch conversation, which CFA Institute Standard of Professional Conduct was most likely violated?
Answer options
Richard Grass is the healthcare analyst for Furrnon Investments and is reviewing the investment merits of the developing hospice industry. The hospice industry has a short history in the public market, as several companies have recently completed their initial public offering. Hospice services are provided to patients diagnosed with terminal illness as an alternative to aggressive medical management. The use of hospice services at skilled nursing facilities and assisted-living facilities is forecasted to continue its recent growth. Medicare is the primary payer for hospice services, accounting for 85% of the approximately $7 billion in industry's revenues. Hospice providers offer symptom and pain management to patients diagnosed with a terminal illness by their physician. The program was added to the Medicare benefit package in the early 1980s. Growth in the sector has only recently. accelerated due to the emergence of a number of for-profit companies. The caregiver provides a plan for each admitted patient and care is given in any number of healthcare environments, including the patient's home. Grass's analysis of the hospice industry has uncovered several facts that are outlined below: • The industry's revenue annual growth rate has increased from 14% in the late 1990s to 25% in 2008. • The average length of stay at facilities for hospice patients is increasing. • Labor costs account for 75% of total expenses, drugs 15% of total expenses, and medical supplies 10%. • More than 80% of hospice patients are above 65 years old and 30% are above 85 years old. • Based on the U.S. Census Bureau's statistics, over the next six years (2009-2015), the number of people in the 65 and older age group will increase annually by 1.4%. • The Medicare hospice benefit is still underutilized by the terminally ill population, according to MedPac (an independent advisory committee for the U.S. Congress on healthcare issues). • Only 30% of Medicare beneficiaries enroll in the hospice benefit before they die. • In recent years, the U.S. government has approved rate increases for the sector compared to flat or declining rate trends for other healthcare services. • The Medicare hospice program has a beneficiary cap which cannot exceed approximately $18,000 annually per person. • The top six for-profit providers account for about half of the segment's sales. • The overall hospice provider market is roughly divided into 55% non-profit, 10% U.S. government, and 35% for-profit. Grass's analysis has narrowed his search to Hope Company. Hope controls about 7% of the total hospice service market or 20% of the for-profit market. The company has the only regulator approved for-profit certificate for the state of Florida, one of the most attractive markets in the United States. In addition to a strong market share in Florida, Hope has a strong presence in urban markets like Dallas and San Francisco. Hope has a more diversified revenue base than other publicly traded for-profit providers. Grass's research report on Hope Company is positive on its investment merits. Grass's report states, "Hope is uniquely positioned in the hospice industry" Which of the following best supports his comment?
Answer options
Yi Tang updates several economic parameters monthly for use by the analysts and the portfolio managers at her firm. If economic conditions warrant, she will update the parameters even more frequently. As a result of an economic slowdown, she is going through this process now. The firm has been using an equity risk premium of 5.6%, found with historical estimates. Tang is going to use an estimate of the equity risk premium found with a macroeconomic model. By comparing the yields on nominal bonds and real bonds, she estimates the inflation rate to be 2.6%. She expects real domestic growth to be 3.0%. Tang does not expect a change in price/earnings ratios. The yield on the market index is 1.7% and the expected risk-free rate of return is 2.7%. Elizabeth Trotter, one of the firm's portfolio Managers, asks Tang about the effects of survivorship bias on estimates of the equity risk premium. Trotter asks, "Which method is most susceptible to this bias, historical estimates, Gordon growth model estimates, or survey estimates?" Tang wishes to estimate the required rate of return for Northeast Electric (NE) using the Capital Asset Pricing Model (CAPM) and the Fama-French three factor model. She is using the following information to accomplish this: · The risk-free rate of return is 2.7%. · The expected risk premiums arc: CFA Institute CFA LEVEL II question · The beta coefficient in the CAPM is estimated to be 0.63. · The betas (factor sensitivities) for the three Fama-French factors are 1.00 for the market factor, - 0.76 for the size factor, and -0.04 for the book-to-markct factor. Trotter also asks Tang about adjusted betas. She says, "We use a formula for the adjusted beta where the adjusted beta = (2/3) (regression beta) + (1/3) (1.0). How do the adjusted betas compare to the original regression betas?" Trotter has one final question for Tang. Trotter says, "We need to estimate the equity beta for VixPRO, which is a private company that is not publicly traded. We have identified a publicly traded company that has similar operating characteristics to VixPRO and we have estimated the beta for that company using regression analysis. We used the return on the public company as the dependent variable and the return on the market index as the independent variable. What steps do I need to take to find the beta for VixPRO equity? The companies have different debt/equity ratios. The debt of both companies is very low risk, and I believe I can ignore taxes." The required rate of return for NE estimated with the Fama-French three factor model is closest to:
Answer options
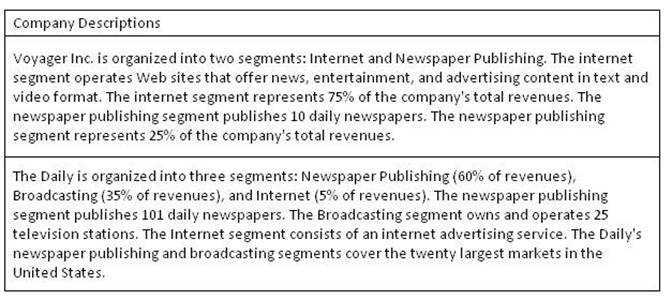
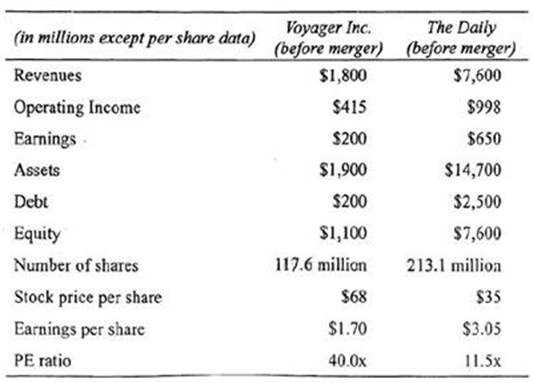
Voyager Inc., a primarily internet-based media company, is buying The Daily, a media company with exposure to newspapers, television, and the internet. CFA Institute CFA LEVEL II question Voyager's acquisition of The Daily is The company's second major acquisition in its history. The previous acquisition was at the height of the merger boom in the year 2000. Voyager purchased the Dragon Company at a premium to net asset value, thereby doubling the company's size. Voyager used the pooling method to account for the acquisition of Dragon; however, because of FASB changes to the Business Combination Standard, Voyager will use the acquisition method to account for the Daily acquisition. CFA Institute CFA LEVEL II question Voyager has made an all-cash offer of $45 per share to acquire The Daily. Wall Street is skeptical about the merger. While Voyager has been growing its revenues by 40% per year, The Daily's revenue growth has been less than 2% per year. Michael Renner. the CFO of Voyager, defends the acquisition by stating that The Daily has accumulated a large amount of tax losses and that the combined company can benefit by immediately increasing net income after the merger. In addition, Renner states that the New Voyager will eliminate the inefficiencies of the internet operations and thereby boost future earnings. Renner believes that the merged companies will have a value of $17.5 billion. In the past, The Daily's management has publicly stated its opposition to merging with any company, a position management still maintains. As a result of this situation, Voyager submitted their merger proposal directly to The Daily's board of directors, while the firm's CEO was on vacation. Upon returning from vacation, The Daily's CEO issued a public statement claiming that the proposed merger was unacceptable under any circumstances. Which of the following best characterizes Voyager's proposal to merge with The Daily?
Answer options
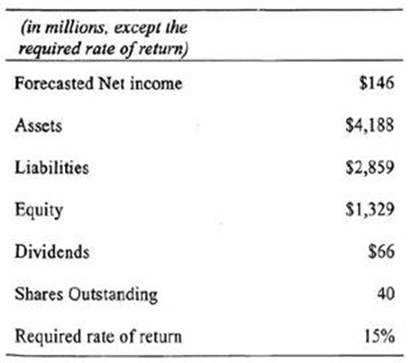
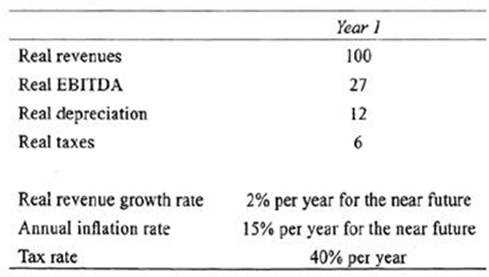
Janice Palmer, CFA, is an international equity analyst at a large investment management firm catering to high net worth U.S. investors. She is assisted by Morgan Greene and Cathy Wong. Both Greene and Wong have prepared their preliminary security selections and are meeting along with Palmer today for detailed security analysis and valuation. They have narrowed their focus to a few closed-end country funds and some firms from Switzerland, Germany, the U.K. and the emerging markets. The initial decision is to choose between closed-end country funds and direct investment in foreign stock markets. Wong is in favor of country funds because: 1. Country funds provide immediate diversification. 2. Buying country funds is a better choice than direct investment for most emerging markets. However, Wong has observed a premium to NAV that is prevalent in closed-end country funds. Wong is curious as to how the observed premiums would affect investments in such instruments. In contrast to Wong, Greene is more inclined towards individual stocks and has started looking into their financial statements. One firm Greene is analyzing is a German conglomerate. Kaiser Corp. Kaiser has a history of growing by acquiring high-growth firms in niche markets. Exhibit 1 provides key financial information from Greene's analysis of Kaiser Corp. Exhibit 1: Financial information—Kaiser Corp. CFA Institute CFA LEVEL II question While going through their sample of emerging market stocks, Wong observed that these markets in general have high inflation and that sales for the stocks were extremely seasonal. Wong compensated by adjusting reported sales growth in the emerging market firms by deflating the sales using annual inflation adjustments. Wong also made upward adjustments to reported depreciation figures. Wong suggested to her colleagues that they add a country risk premium to the discount rate they were using to evaluate emerging market stocks. She further suggested that they estimate country risk premiums by calculating the spread between the yield of U.S. government bonds and that of similar maturity local bonds. Subsequently they started working on the financial projections for Emerjico, Inc., an emerging market stock. Their assumptions are given in Exhibit 2. Exhibit 2: Key Assumptions—Emerjico CFA Institute CFA LEVEL II question Based on Exhibit 1 and using the dividend discount model (DDM), the intrinsic value of Kaiser Corp is closest to:
Answer options
William Jones, CFA, is analyzing the financial performance of two U.S. competitors in connection with a potential investment recommendation of their common stocks. He is particularly concerned about the quality of each company's financial results in 2007-2008 and in developing projections for 2009 and 2010 fiscal years. Adams Company has been the largest company in the industry but Jefferson Inc. has grown more rapidly in recent years. Adams's net sales in 2004 were 33-1/3% higher than Jefferson but were only 18% above Jefferson in 2008. During 2008, a slowing U.S. economy led to lower domestic revenue growth for both companies. The 10-k reports showed overall sales growth of 6% for Adams in 2008 compared to 7% for 2007 and 9% in 2006. Jefferson's gross sales rose almost 12% in 2008 versus 8% in 2007 and 10% in 2006. In the past three years, Jefferson has expanded its foreign business at a faster pace than Adams. In 2008, Jefferson's growth in overseas business was particularly impressive. According to the company's 10-k report, Jefferson offered a sales incentive to overseas customers. For those customers accepting the special sales discount, Jefferson shipped products to specific warehouses in foreign ports rather than directly to those customers' facilities. In his initial review of Adams's and Jefferson's financial statements, Jones was concerned about the quality of the growth in Jefferson's sales, considerably higher accounts receivables, and the impact of overall accruals on earnings quality. He noted that Jefferson had instituted an accounting change in 2008. The economic life for new plant and equipment investments was determined to be five years longer than for previous investments. For Adams, he noted that the higher level of inventories at the end of 2008 might be cause for concern in light of a further slowdown expected in the U.S. economy in 2009. The accompanying table shows financial data for both companies' Form 10-k reports for 2006-2008 used by Jones for his analysis. To evaluate sales quality, he focused on trends in sales and related expenses for both companies as well as cash collections and receivables comparisons. Inventory trends relative to sales and the number of days' sales outstanding in inventory were determined for both companies. Expense trends were examined for Adams and Jefferson relative to sales growth and accrual ratios on a balance sheet and cash flow basis were developed as overall measures of earnings quality. The quality of earnings as measured by balance sheet based accruals ratios showed:
Answer options
Question 1 of 10

Source context

How this practice set is maintained

Maintained by the CertMage content team, this page loads questions from the exam dataset connected to its preparation resource. When an answer includes a supporting reference, it is shown with that answer so you can review the underlying vendor documentation.

Certification objectives, interfaces, and vendor services can change. Verify important details against the provider's current exam guide and documentation before your exam.

Scroll to Top